Can I register for Hajj 2027 at Meezan Bank?
Meezan Bank's Hajj adverts make it sound like a one-stop shop. It isn't. Here's what the bank actually does for Hajj 2027, what it doesn't, and where your government application actually needs to land.
Can I register for Hajj 2027 at Meezan Bank, or just finance it?
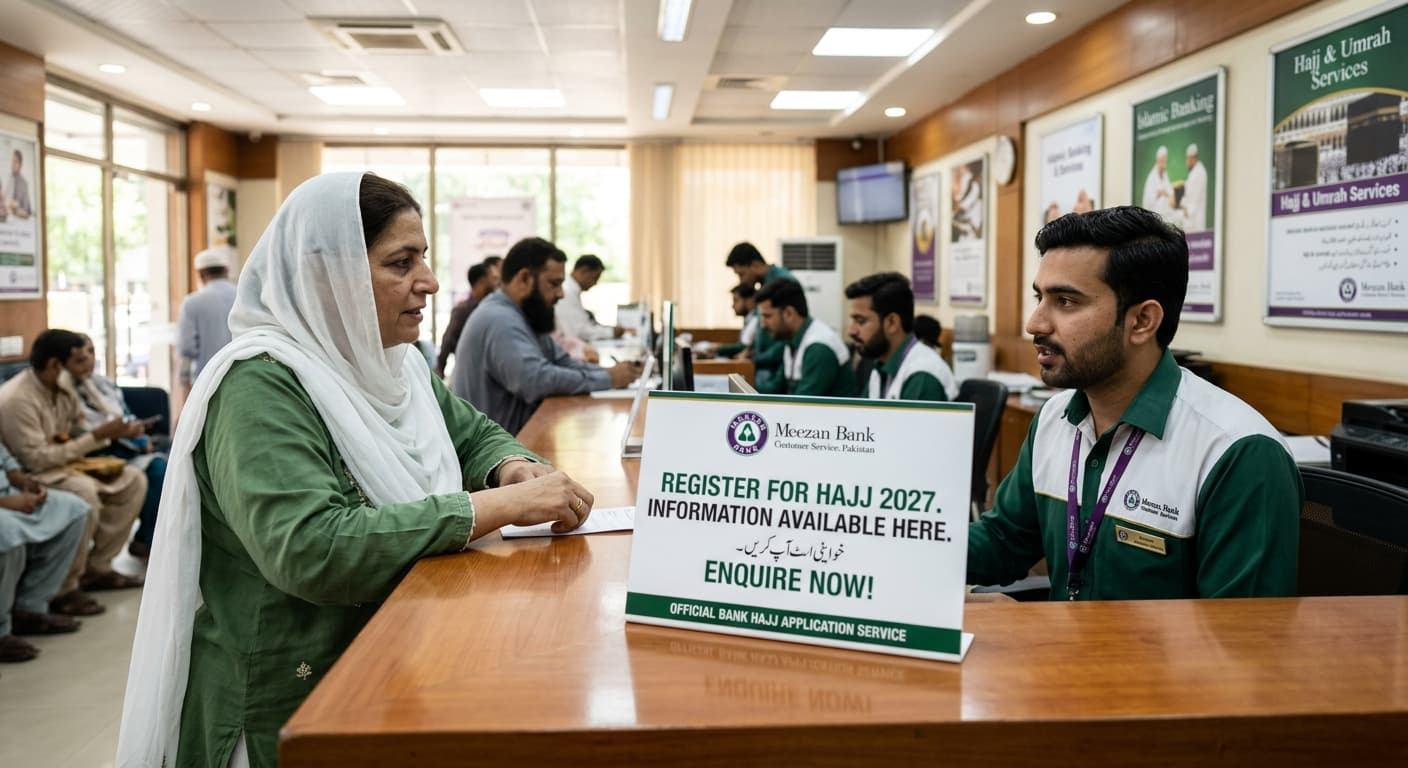
You can finance Hajj through Meezan Bank. You cannot register for Hajj 2027 at Meezan Bank in the official, government-scheme sense. The Ministry of Religious Affairs commenced Hajj 2027 registration on June 22, 2026, according to Allied Bank, and that registration happens through the Ministry's own online portal and the branches it specifically designates for the Government Hajj Scheme that year.
Meezan Bank's branch network is not automatically one of those designated intake points, and this is the single most common confusion around the whole topic. The bank's Hajj product, branded Labbaik, is a private financing and savings arrangement that sits next to the government process. If a branch is accepting government forms in a given year, it's because the Ministry has named it, not because it's a Meezan Bank branch.
So where does the actual government form go?
Check the Ministry of Religious Affairs' Hajj portal directly, every cycle, because the list of participating banks and designated branches changes year to year. Don't assume last year's list carries over. This is the part people skip, and it's the part that actually decides whether your paperwork lands anywhere.
What Meezan Bank is actually selling you
Meezan Bank's relevant product is called Labbaik Travel Asaan, an installment financing facility built for Hajj and Umrah travel costs. You pick a package, usually through a partner travel agent, and the bank finances the balance after your down payment under an Islamic financing structure (no interest in the conventional sense, structured instead around a cost-plus or lease arrangement, depending on the product variant).
The terms are specific enough to write down. Meezan Bank requires a minimum 50% down payment for Hajj under its Labbaik installment facility, per Meezan Bank. The maximum repayment tenor on that financing is 12 months. Monthly installments cannot exceed 40% of your net monthly income, which is the bank's Debt Burden Ratio ceiling, and there's a processing fee of roughly Rs. 3,000 attached to the facility.
If you can't put down half the package cost in one go, this product isn't going to get you to Mina.
Worked example
Say a private Hajj package runs Rs. 1,200,000. Under Labbaik Travel Asaan you'd need roughly Rs. 600,000 upfront. The remaining Rs. 600,000 gets spread over up to 12 months, so you're looking at Rs. 50,000-plus monthly before the bank even checks whether that fits inside 40% of your take-home pay. For a lot of salaried applicants, that income test is the real wall, not the down payment.
Government Hajj Scheme versus Meezan Bank's private route
Factor | Government Hajj Scheme | Meezan Bank (Labbaik, private) |
|---|---|---|
Who runs it | Ministry of Religious Affairs | Meezan Bank + partner travel agents |
Where you apply | Ministry's online portal, designated branches | Meezan Bank branch or digital banking channel |
Cost structure | Generally lower, subsidised quota | Package price plus financing cost, generally higher |
Selection | Balloting if demand exceeds quota | First-come, subject to financing approval |
Payment | Usually full or scheduled Ministry payment plan | 50% down, up to 12-month installments |
Nobody publishes a clean side-by-side cost comparison between a Meezan Bank partner package and the government scheme, and that's a real gap worth naming rather than glossing over. Government quotas are usually cheaper per pilgrim because there's no agent margin and no financing markup stacked on top. The private route costs more precisely because you're paying for speed, flexibility, and a specific agent's service level, not a cheaper seat.
The register for Hajj 2027 at Meezan Bank Labbaik Saving Asaan account, and why it's not the same thing as financing
This one trips people up too. Meezan Labbaik Saving Asaan is a Mudarabah-based deposit account, not a loan product. You put money in over months or years, it earns profit under the bank's Islamic deposit structure, and the idea is that you arrive at Hajj season needing less financing, not more.
If you start this account three years out, the math changes considerably. Someone saving Rs. 40,000 a month for 24 months builds close to Rs. 960,000 before profit, which on a typical package could mean skipping the installment facility altogether. That's the quieter, less-marketed route: use the savings account early, use Labbaik Travel Asaan only for the shortfall.
What nobody selling you this product tells you upfront
The eligibility screen isn't just income, it's your existing debt. A car loan or a running credit card balance eats into that 40% Debt Burden Ratio ceiling before Hajj financing even enters the picture. Two applicants earning identical salaries can get completely different approval outcomes because one of them already carries other financing.
Worth saying plainly: the bank will approve what fits its risk model, not what fits your actual travel plan. If the numbers don't work for the 12-month tenor, the answer isn't to find a workaround, it's to extend your savings timeline instead.
Anyway. The confusion at the center of all this is really just branding doing its job too well. Meezan Bank didn't build a government registration desk. It built a financing product with a Hajj-flavored name, and that's a perfectly reasonable thing for a bank to do. It just means the question "can I register for Hajj 2027 at Meezan Bank" has a different answer depending on whether you mean the paperwork or the payment.
Frequently asked questions
Can I submit my Government Hajj Scheme 2027 application at a Meezan Bank branch?
No. The Government Hajj Scheme application goes through the Ministry of Religious Affairs' own portal and the branches it specifically designates that year, not through Meezan Bank's general branch network. Check the Ministry's current list before assuming any particular bank qualifies.
What is the down payment requirement for Meezan Bank Hajj financing?
Meezan Bank requires a minimum 50% down payment under its Labbaik installment facility, per Meezan Bank. The remaining balance is financed over a tenor of up to 12 months.
How does the Meezan Labbaik Saving Asaan account work for Hajj?
It's a Mudarabah savings account, not a loan. You deposit money regularly ahead of your intended travel year, it earns profit, and the balance you build reduces how much Labbaik financing you'll need later.
What documents are required to apply for Meezan Bank Labbaik Travel Asaan financing?
Typically your CNIC, proof of income, recent bank statements, and documentation that lets the bank calculate your Debt Burden Ratio against the 40% ceiling. Branch requirements can vary slightly, so confirm the current list before you show up expecting a same-day decision.